
Un cambio de paradigma para el crédito al consumo en España
Publicado en Iberian Lawyer el 08-04-2026
08-04-2026 — CM/2026/053
Spain’s consumer credit market is undergoing a profound regulatory shift. Providers will be required to obtain prior authorisation from the Bank of Spain and will become subject to ongoing supervisory oversight. At the same time, stricter conduct of business rules and tighter limits on credit fees and costs will significantly raise the compliance threshold for market participants — marking a turning point for the sector.
On 7 January 2026, the Spanish Government submitted for public consultation the draft bill on consumer credit together with its implementing draft royal decree. These texts partially implement Directive (EU) 2023/2225 on consumer credit and fully transpose Directive (EU) 2023/2673 on distance marketing of financial services, representing a decisive step towards a profound reform of the Spanish consumer credit market.
Although the final texts still need to be approved —the bill must be submitted to Parliament to begin the legislative process— the combined effect of the draft bill and the draft royal decree already signals a clear policy shift. Spain appears to be moving from a framework largely shaped by case law and ex post enforcement to a more prescriptive regime, characterised by ex ante constraints on pricing, expanded supervisory oversight and significantly reinforced conduct obligations. This transition also comes at a time when EU implementation deadlines have already passed —20 November 2025 for consumer credit and 19 December 2025 for distance marketing— increasing legal uncertainty for market participants.
The new framework substantially expands the regulatory perimeter. Once adopted, it will apply to professional lenders and credit intermediaries operating in the Spanish consumer credit market, regardless of their legal form and whether they are based in Spain or operate cross-border. Microlenders and high-cost credit providers, traditionally active at the margins of regulation, are explicitly brought within scope. Only narrowly defined exemptions remain for SMEs and micro-enterprises granting interest-free or low-cost deferred payment as a purely ancillary activity.
One of the most disruptive elements of the reform is the introduction of statutory interest rate caps. For the first time, Spanish law will impose mandatory limits on the total cost of consumer credit, expressed as APR, with dynamic caps to be set and published by the Bank of Spain for different credit segments. Pending the adoption of the implementing regulation, a transitional cap of 22% APR will apply to new credit and, in certain cases, to existing credit arrangements. Where the applicable cap is exceeded, interest and costs become unenforceable, leaving the consumer obliged to repay only the principal.
Rather than prohibiting high-cost lending, the Spanish legislator has opted to formalise it. A new category of authorised high-cost lenders will require a Bank of Spain licence and will be subject to capital requirements, enhanced transparency and conduct rules. The reform also strengthens consumer protection throughout the credit lifecycle, expanding advertising and pre-contractual disclosure obligations and reinforcing solvency assessments under a responsible lending approach.
For international lenders and intermediaries, the implications are significant. The combination of delayed implementation expanded supervisory powers for the Bank of Spain and binding price caps creates a landscape in which legacy assumptions will quickly become obsolete. Early and strategic engagement with the evolving regulatory framework will therefore be essential as Spain moves towards one of the most interventionist consumer credit regimes in the EU.
Últimas noticias (ver todas)
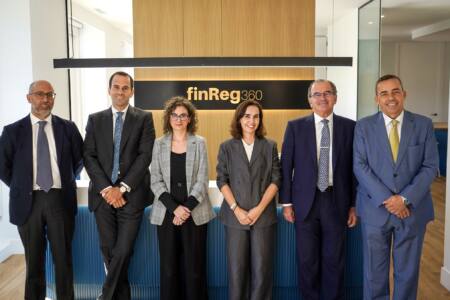
finReg360 integra a su equipo a seis nuevos profesionales
finReg36014-10-2026
Jorge Ferrer, socio cofundador de finReg360, ha destacado que «estas incorporaciones permiten diversificar la oferta de la firma hacia el derecho administrativo y la resolución de disputas, consolidando la práctica transversal de seguros y previsión social».
En Intereconomía el 14-10-2026 finReg360 refuerza su área de Regulación Financiera con la incorporación de seis profesionales procedentes del despacho Álvaro Requeijo Abogados
finReg36014-10-2026
Álvaro Requeijo Pascua se unirá como counsel, Álvaro Requeijo Torcal lo hará como director y a ellos los acompañarán los abogados Mercedes Villarrubia, Ana Risco, Pelayo Vidal y Pedro Arévalo.
En Economist & Jurist el 14-10-2026 finReg360 ficha a seis profesionales para potenciar su área de regulación aseguradora
finReg36014-10-2026
La firma especializada en regulación financiera finReg360 ha incorporado a seis profesionales procedentes de Álvaro Requeijo Abogados para potenciar su área de regulación aseguradora y de pensiones.
En Seguros News el 14-10-2026